


Oct 12 2026
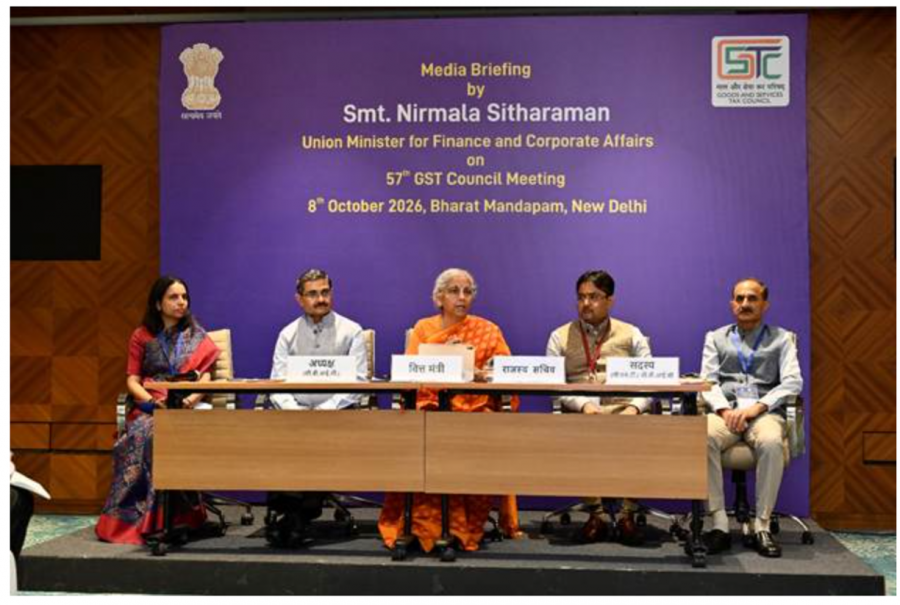
57th GST Council Meeting
In the 57th meeting held on 8th October 2026, GST Council made recommendations relating to process reforms primarily covering registration, returns, refund and adjudication; clarifications regarding applicability of GST on supply of certain goods and services; and other measures for trade facilitation and streamlining compliances in GST.
Specifically regarding SEZs, for refund claims on account of zero-rated supplies (SEZ to DTA), in phase 1, 90% of the amount claimed will be sanctioned on provisional basis automatically by the system, without officer intervention, on the basis of identification and evaluation of risk by the system and in phase 2, there will be system-based automated acknowledgment (without officer intervention) on due verification of the refund application by the system and in such acknowledged cases, automated sanction of full refund claim by the system (without officer intervention), in respect of claims pertaining to zero rated supplies, after adjusting pending dues, if any, on the basis of identification and evaluation of risk by the system. GST Council also recommended insertion of an explanation to section 16(1) of the IGST Act, 2017 to provide that in the cases where goods are supplied to an overseas buyer, but the delivery of goods is made to the said buyer in an SEZ/FTWZ, and the payment for such supply is received in convertible foreign exchange or in Indian Rupees wherever permitted by the RBI, then such a supply will be deemed to be supply of goods to an SEZ/FTWZ. This will provide certainty regarding zero rating benefit to Indian manufacturers making supply of goods for overseas buyers by making delivery to them in an SEZ/FTWZ for warehousing or further processing.
Latest Events
-
57th GST Council MeetingOct 12 2026
-
SEEPZ SEZEPC participated in Economic Review Meet of EXIM BankOct 07 2026
-
BRICS declaration addresses trade restrictions and WTO reformSep 12 2026 - Sep 13 2026
-
BRICS Business Forum in New Delhi - Commerce and Industry Minister Shri Piyush Goyal Calls for Deeper, Resilient and More Balanced Intra-BRICS TradeSep 12 2026 - Sep 13 2026
-
BRICS Business Forum in New Delhi - Commerce and Industry Minister Shri Piyush Goyal Calls for Deeper, Resilient and More Balanced Intra-BRICS TradeSep 12 2026 - Sep 13 2026